
Table of Contents
FCNR(B) deposits and the RBI swap facility, explained in simple words
Between 8 June and 31 August 2026, Non-Resident Indians (NRIs) put about $127.23 billion into FCNR(B) deposits with Indian banks. Banks offered 6% to 6.5% a year on 3 to 5 year dollar deposits. The money was nearly five times what the RBI raised through a similar scheme in 2013. This is the story of the 2026 FCNR(B) swap.
You would expect the rupee to rally on such a flood of dollars. It did not. Between 8 June and 17 August it moved from 95.71 to 95.60 per dollar, a gain of just 0.1%. So why were banks so generous, and where did the dollars go? This is the first of two articles. Here we explain the deposit and the swap in simple words. In the next one, we look at what the scheme did to bank profits.
Quick answer
FCNR(B) is a fixed deposit of 1 to 5 years in a foreign currency such as the US dollar, opened by an NRI with an Indian bank. Principal and interest are tax-free in India and are repaid in the same currency, so the NRI carries no rupee risk.
The 2026 RBI swap facility (8 June to 31 August, cut short from 30 September) let banks hand the dollars from 3 to 5 year FCNR(B) deposits to the RBI, take rupees today, and buy the same dollars back at maturity at the same rate. The hedging cost to the bank was zero.
Result: $127.23 billion came in, but the rupee barely moved, because the RBI took the dollars directly, used them to rebuild reserves and settle its forward contracts, and many NRIs borrowed dollars back against their own deposits.
What is an FCNR(B) deposit?
FCNR(B) stands for Foreign Currency Non-Resident (Bank) account. Think of it as a fixed deposit that is kept in dollars, pounds or euros instead of rupees.
Imagine Ramesh, an engineer in Houston, with $50,000 in savings. He opens a three-year FCNR(B) deposit with an Indian bank. At maturity, he gets his dollars back with dollar interest. Whatever the rupee does in between does not matter to him.
| Feature | FCNR(B) deposit |
|---|---|
| Who can open | NRIs, PIOs and OCIs (residents of Nepal and Bhutan are excluded; Pakistan and Bangladesh nationals need RBI approval) |
| Type of account | Term deposit only. No savings, current or recurring accounts |
| Tenor | 1 year to 5 years |
| Currencies | USD, GBP, EUR, JPY, AUD, CAD, SGD |
| Interest | Paid in the same currency. Calculated on an actual/360 day year and compounded every 180 days |
| Normal rate cap | Overnight benchmark rate (SOFR for dollars) or swap rate, plus 2.50% for 1 to under 3 years and plus 3.50% for 3 to 5 years |
| Tax in India | Principal and interest are tax-free for non-residents. Freely repatriable |
| Early withdrawal | Before 1 year, no interest is paid |
| Who bears currency risk | The bank |
Source: RBI Interest Rate on Deposits Directions, 2025. SOFR is the overnight dollar benchmark rate that replaced LIBOR.
If an NRI returns to India and becomes a resident, the deposit can run to maturity at the same rate. Banks do not deduct TDS on FCNR(B), so interest earned after the change of status must be self-reported.
Who takes the currency risk?
Under the old FCNR(A) scheme of 1975, the RBI and the government carried the exchange risk. Since 15 May 1993, FCNR(B) has put that risk on the bank. Banks usually protect themselves by hedging, and hedging costs money. SBI Research and other analysts put that cost at about 3.00% to 3.50% a year in 2026.
FCNR(B) vs NRE vs NRO: what is the difference?
| Point | FCNR(B) | NRE | NRO |
|---|---|---|---|
| Currency | Foreign currency | Indian rupee | Indian rupee |
| Account types | Term deposit only | Savings, current, recurring, term | Savings, current, recurring, term |
| Tax in India | Tax-free | Tax-free | Taxable (TDS applies) |
| Who bears rupee risk | The bank | The depositor | The depositor |
| Best for | Foreign earnings you want to keep in foreign currency | Foreign earnings you want to use in rupees | Indian income such as rent and dividends |
Source: RBI rules on FCNR(B), NRE and NRO accounts. For more on account types, see our Account Types section.
What is a currency swap?
A swap is a deal done in two steps. You exchange two currencies today. You also agree to exchange them back on a fixed future date, at a price fixed today.
Here is a simple picture. You give a friend $100 today and take ₹9,500. You agree that after five years you will hand back exactly ₹9,500 and take back exactly $100, whatever the market rate then. You are protected. Your friend carries the risk: if the rupee falls to 105, that $100 is worth ₹10,500, but your friend receives only ₹9,500.
The rupee tends to weaken over the long run, so the person who takes that risk normally charges a fee, called a swap premium. In 2013, when the RBI ran a similar scheme, banks paid it 3.50% a year. In 2026, the RBI charged nothing.
| 2013 FCNR(B) swap | 2026 FCNR(B) swap | |
|---|---|---|
| Window | 10 Sept to 30 Nov 2013 | 8 June to 31 Aug 2026 (cut short from 30 Sept) |
| Swap cost to the bank | 3.50% a year | 0% (swap at par) |
| Deposit rate cap | Benchmark + 4.00% | Cap removed for 3 to 5 year deposits from 17 June 2026 |
| Money raised | About $24.5 to 26 billion | $127.23 billion |
| Rupee move (2026: 8 June to 17 Aug) | Up 4.9% (65.70 to 62.45) | Up about 0.1% by 17 Aug (95.71 to 95.60) |
Source: RBI circulars RBI/2013-14/234 and RBI/2026-27/99; SBI Research; CareEdge.
How the 2026 RBI swap facility worked
The RBI announced the facility on 5 June 2026 and started it on 8 June. It had planned to run to 30 September, but on 14 August it advanced the cut-off to 31 August, after strong inflows. Here is the flow for a fresh or renewed FCNR(B) deposit of 3 to 5 years.
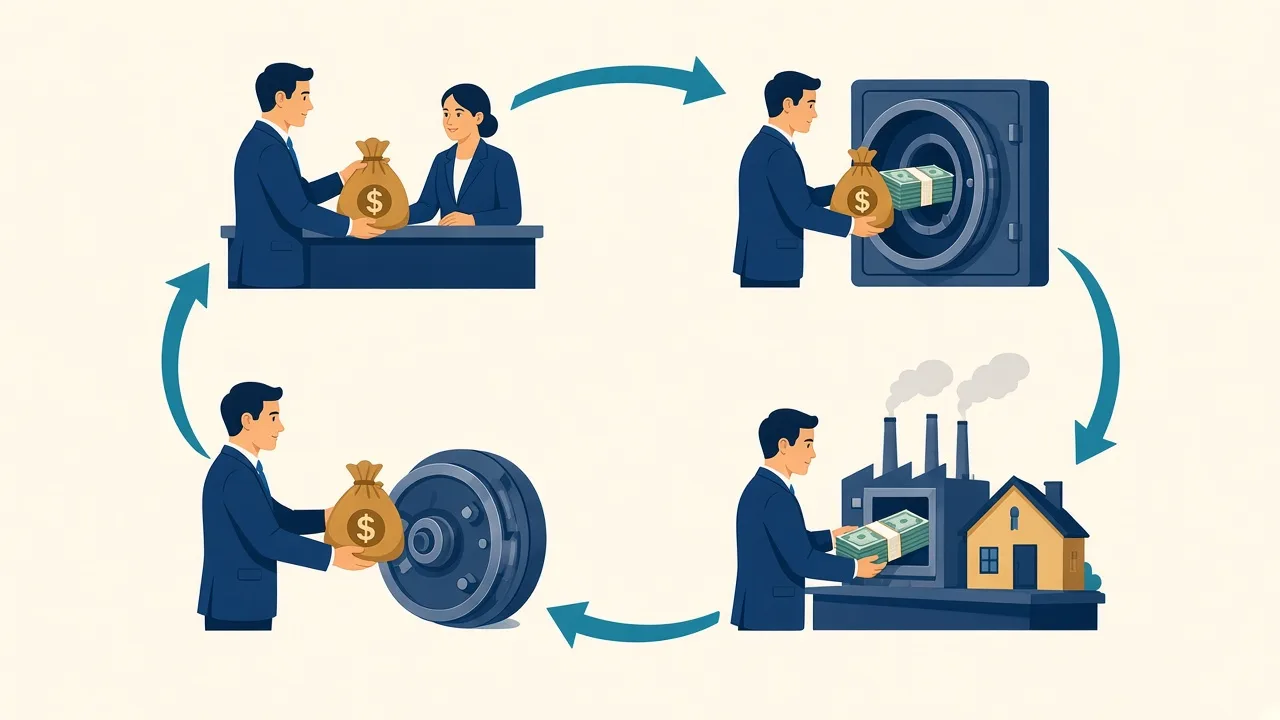
- An NRI opens a 3 to 5 year FCNR(B) deposit in dollars.
- The bank sells those dollars to the RBI (in multiples of $1 million) at that day’s FBIL reference rate and receives rupees.
- The bank lends or invests those rupees in India.
- At maturity, the bank buys the same dollars back from the RBI at the same reference rate and repays the NRI.
An example with round numbers. Say the rate is ₹95 per dollar. An NRI deposits $1 million. The bank gets ₹9.5 crore from the RBI today. Five years later, even if the rupee has slipped to ₹105, the bank still buys its $1 million back for ₹9.5 crore. Without the swap, it would have needed ₹10.5 crore. The RBI carries that ₹1 crore difference. These numbers are only for illustration.
Only the principal was swapped, so banks managed the interest part themselves.
Why banks paid up to 6.5% on dollar deposits
Normally, a bank cannot afford to pay 6.5% on a dollar deposit and still lend profitably. The big cost in the way is hedging, about 3% to 3.5% a year. On a 6% dollar deposit, the hedge alone would push the real cost to about 9% (our arithmetic), too high to lend against. The RBI removed that cost, and then removed four more frictions.
| Relaxation | What it means in simple words |
|---|---|
| 1. Swap at par | No hedging cost for the bank. This alone saved about 3.00% to 3.50% a year. |
| 2. No rate cap (from 17 June) | Banks could pay what they liked on 3 to 5 year deposits. Dollar rates of 6.00% to 6.50% followed (HDFC, ICICI and Axis at 6.00%; Kotak at 6.15%; Canara at 6.50%). |
| 3. No CRR or SLR | Normally, a slice of every deposit must sit with the RBI as cash (CRR) or in government securities (SLR). These deposits were exempt, so banks could use 100% of the money. |
| 4. No priority sector burden (from 7 August) | Normally, 40% of new lending must go to priority sectors such as agriculture. Loans against these deposits were left out of the base used for that target. |
| 5. Position limits relaxed | The RBI had capped banks’ net rupee position at $100 million a day. Hedged FCNR(B) swaps were kept out of that cap. |
Source: RBI circulars RBI/2026-27/99, /102 to /106, /138, /232 and A.P. (DIR Series) Circulars 13 and 16.
Leveraged FCNR(B): borrowing to deposit
The biggest surprise came in the last ten days. FCNR(B) inflows jumped from $65.40 billion on 21 August to $127.23 billion on 31 August. Almost half the money came in during the final stretch.
The reason was a rule change. The RBI allowed banks, including their overseas branches and GIFT City units, to give foreign currency loans to NRIs against these deposits, or to issue standby letters of credit. This created the “leveraged FCNR(B)” idea. An NRI puts in some of their own money, borrows nine to twelve times that amount abroad, and books one very large deposit.
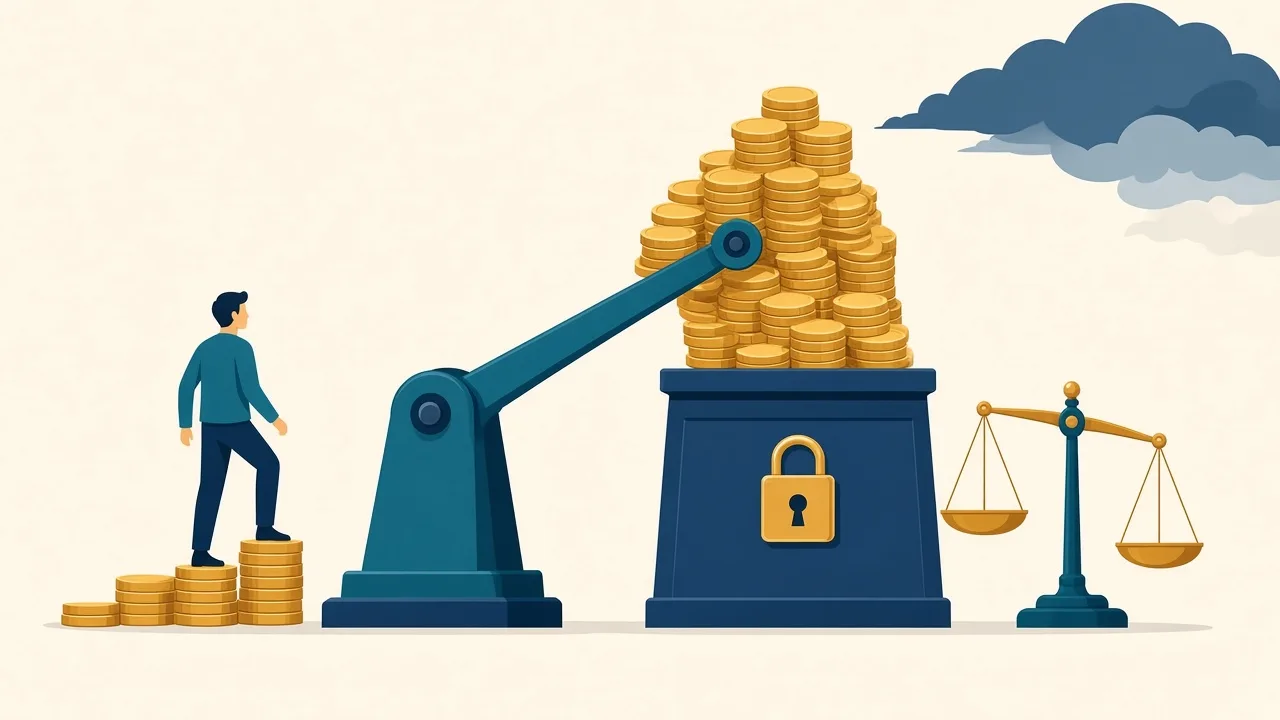
Here is the 3 year, 9x illustration from Kotak Mahindra Bank’s product guide:
| Item | Amount |
|---|---|
| NRI’s own money | $1,000,000 |
| Foreign currency loan (9x) | $9,000,000 |
| FCNR(B) deposit booked | $10,000,000 |
| Deposit rate (compounded every 6 months) | 6.15% a year |
| Loan rate (simple interest) | 6.00% a year |
| Deposit interest over 3 years | $2,023,517 |
| Loan interest over 3 years | $1,620,000 |
| Net gain | $403,517 |
| Return on own money | About 13.45% a year |
Source: Kotak Mahindra Bank leveraged FCNR guide, July 2026. At 12x, the same bank’s illustration shows about 15.69% a year. Illustrations only, not a promise of returns.
The gap between the two rates is just 0.15%. The profit comes from scale and compounding: the deposit earns interest on interest every six months, while the loan charges simple interest.
The risks
- Tax mismatch. Some countries, such as the US, may tax the gross deposit interest ($2.02 million here), not just the $403,517 net gain.
- Rate reset risk. If the loan is linked to a floating rate such as SOFR, the cost can rise.
- No exit. The bank holds a lien on the deposit, and there is a one-year lock-in.
NRIs in the UAE had an edge, as the dirham is pegged to the dollar and personal income tax is zero. NRIs elsewhere should check taxes first.
Why did the RBI do this?
The RBI needed dollars, quickly:
- Oil and the current account. Tension in West Asia pushed oil close to $90 a barrel. India’s current account deficit for April to August 2026 widened to an estimated $18.3 billion, from $12.8 billion a year earlier (the RBI publishes official figures only quarterly).
- Costly dollars abroad. The 30 year US Treasury yield rose to nearly 5.3%, its highest since 2007.
- A weak rupee. It crossed 90 per dollar in December 2025 and touched 96.28 on 17 July.
- A record short forward book. To defend the rupee, the RBI had sold dollars for future delivery. This “short forward book” hit a record $136.7 billion in July, up from $103.3 billion in June, and the RBI needed actual dollars to deliver on it.
The inflows shifted India’s balance of payments into a substantial surplus in the July to September quarter (Q2 FY27), but it is expected to turn negative again in the second half of FY27 (Gaura Sen Gupta, chief economist, IDFC FIRST Bank, writing in Business Standard, 1 October 2026).
Did the rupee get stronger?
Hardly. In 2013, the rupee gained 4.9% during the window. In 2026, about 0.1% by 17 August, the latest date in our data. Four reasons:
- The RBI took the dollars directly. Banks swapped dollars with the RBI at a fixed rate, not in the open market. So there was no buying pressure on the rupee. The RBI used them to rebuild its foreign currency assets and settle its forward contracts. Reserves reached $729.3 billion by 21 August.
- Some dollars went right back out. Overseas branches and GIFT City units lent dollars to the same NRIs. August saw a net outflow of $22.4 billion under external commercial borrowings. Economists differ on the exact cause, but Kotak’s chief economist linked it to GIFT City units lending to non-residents. ICICI Bank, for example, said in an exchange filing that it mobilised $17.88 billion in FCNR(B) deposits, with around $9 billion in overseas loans and $3.63 billion in standby letters of credit against them (provisional and unaudited figures, as reported by Upstox and Business Standard). Net new money was much smaller than the headline.
- The cost sits with the RBI. SBI Research estimated that at 3% a year, a $70 billion corpus costs about $2.1 billion annually. On $127 billion, the same 3% would be roughly $3.8 billion a year (our arithmetic).
- Rupee cash flooded the system. Every dollar the RBI took gave banks matching rupees. We look at that next.
What happened to rupee liquidity?
The swaps poured rupees into the banking system. Surplus liquidity rose to ₹6.65 lakh crore on 31 August (the highest since May 2022) and nearly ₹10.5 lakh crore by 9 September. The RBI drained it through reverse repo auctions, ₹1 lakh crore of bond sales and a 25 basis point repo rate hike on 7 October.
Is the window still open? What happens next?
- The FCNR(B) swap window is closed, and it was not extended. It was planned to run to 30 September, but the RBI advanced the cut-off to 31 August. Banks could still execute swaps for deposits raised by then until 11 September. Regular FCNR(B) deposits continue under normal rules.
- The company and bank borrowing window is still open. The swap for external commercial borrowings and bank overseas borrowings runs to 31 December 2026, at 1.50% a year.
- A maturity wall is coming. These 3 to 5 year deposits fall due between June 2029 and August 2031.
For rupee returns for family in India, try our Bank FD Calculator.
What does this mean for bank profits?
Banks paid 6% to 6.5% on dollars but took three to four months to deploy the money, and earned thin spreads on loans against the deposits. Net interest margins fell by 5 to 22 basis points in Q2 FY27 at large lenders. Yet such loans need almost no extra capital, so return on equity can still improve. We unpack this in our next article.
For real numbers, read our breakdown of Bank of India’s Q2 FY27 results, where about ₹41,400 crore of growth came from this special scheme. Our guide to ROE vs ROCE explains why return on equity is the ratio used for banks, and our P/E vs P/B article shows how bank stocks are valued.
Key takeaways
- FCNR(B) is a 1 to 5 year foreign currency fixed deposit for NRIs, PIOs and OCIs. It is tax-free in India and the bank bears the currency risk.
- The 2026 RBI swap let banks swap the dollar principal of 3 to 5 year deposits with the RBI at par, with no hedging cost, from 8 June to 31 August.
- Leveraged FCNR(B) let NRIs borrow 9 to 12 times their own money against a deposit. Returns look high on paper, but tax, floating rates and lock-ins add real risk.
- The scheme raised $127.23 billion in FCNR(B) deposits, but the rupee moved only about 0.1%, because the RBI absorbed the dollars directly and some money flowed back out through loans.
Frequently asked questions (FAQs)
Is FCNR(B) interest taxable in India?
No. Principal and interest are tax-free for non-residents and freely repatriable. After you become a resident, interest is taxable and you must report it yourself.
What is the RBI FCNR(B) swap facility?
It was a special window from 8 June to 31 August 2026. Banks sold the dollar principal of 3 to 5 year FCNR(B) deposits to the RBI for rupees and agreed to buy the same dollars back at maturity at the same rate, with no swap cost.
Was the FCNR(B) swap window extended to 26 September 2026?
No. We found no extension in any source. The RBI first planned 30 September, then advanced the cut-off to 31 August. Its 21 September press release says the scheme was open till 31 August for FCNR(B) deposits. Banks could execute swaps until 11 September.
Can I still use the swap facility?
Not for FCNR(B). Regular FCNR(B) deposits are still available under normal rules. A separate swap window for company and bank borrowings stays open until 31 December 2026.
Why did the rupee not rise despite $127 billion of inflows?
The RBI took the dollars directly, not through the market, and many NRIs borrowed dollars back against their deposits, so net new money was smaller.
What is a leveraged FCNR(B) deposit?
An NRI adds some own money, borrows nine to twelve times that in foreign currency from an overseas branch or GIFT City unit, and books one large FCNR(B) deposit. It can boost returns but adds tax, rate and liquidity risk.
Disclaimer
This article is for education only and is not investment, tax or legal advice. Figures come from RBI circulars, bank disclosures and published research listed below, and may be rounded. Leveraged FCNR(B) illustrations are bank examples, not promises of returns. Please speak to your bank and a qualified tax adviser before investing. See our full Disclaimer page.
Sources: RBI Interest Rate on Deposits Directions, 2025; RBI circular RBI/2026-27/99; RBI press release, 21 September 2026; Business Standard, 17 August 2026; RBI FAQs on the FCNR(B) swap facility; SBI Ecowrap, 17 August 2026; CareEdge FCNR update, September 2026; Kotak swap window guide; Kotak leveraged FCNR guide; ICICI Bank exchange filing, 2 September 2026 (via Upstox and Business Standard); Business Standard, Gaura Sen Gupta, 1 October 2026. More explainers on our Banking category and Blog page.